Close up image of green wheat head

Sowing is getting underway here, and this generally sees selling slow down as grain growers are busy on tractors rather than filling trucks with old season grain, or at the computer looking at new season prices. While there is nothing screaming sell at the moment, things are looking more positive.

Wheat prices seem to have found a floor and are heading in the right direction if you are a seller. Since moving into the lower $300/t range in our terms, CME Soft Red Wheat (SRW) has had a bounce, with new crop futures now at $340/t (figure 1).

The drivers of wheat market support are the wet weather in Europe, but this is only really offsetting continued good news on wheat crops coming out of the US and Russia. The pullback of corn acreage in the US, as Friday’s comment outlined, should add some support for the grain complex in general.

The average corn yield last year was 11t/ha, but the reduction in plantings is in marginal corn areas. Even if we use a yield of 8t/ha, the 2.55 million hectare reduction equates to 20 million tonnes.  The lower production is roughly double the Australian barley crop, and is a lot of grain.

Figure 1 shows local new crop prices are now moving in sync with US values.  Basis has remained steady around parity with SRW, with ASX futures currently sitting around $340-350/t. Basis around parity is consistent with a better than average crop, and recent rain through significant eastern cropping areas is likely to have helped confirm this view.

Canola prices have managed to hold on to the increases seen during March, both in international markets and locally. Slow, and eventually lower, expected sowing rates in Europe have given canola prices a boost, and our prices have tracked them closely.

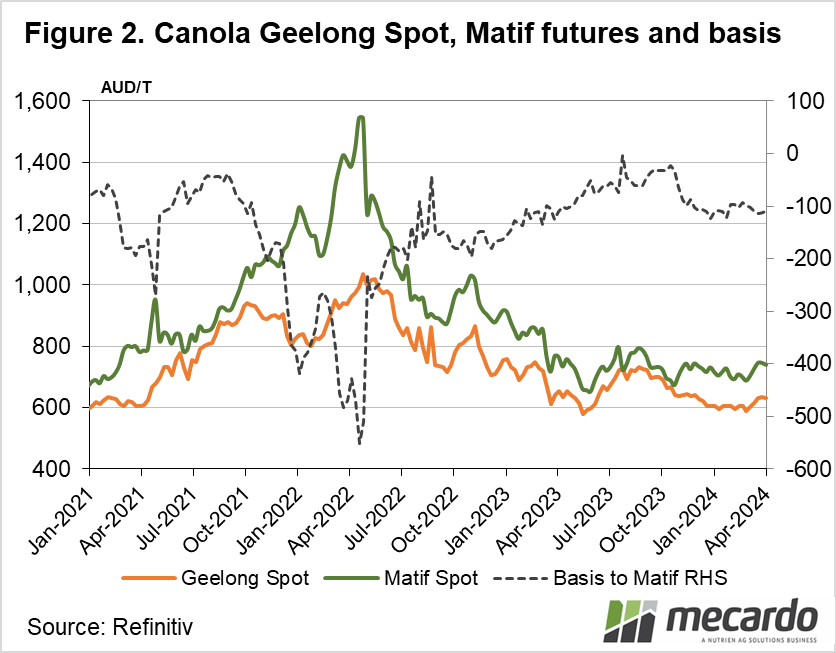
Figure 2 shows canola values are still at the bottom of the three year range, but in the absence of a serious black swan event in the oilseed complex, it’s hard to see them heading back to the prices of 2022.     
Prices finding a floor is good for markets, but there is always a chance it could be a dead cat bounce. During good years prices tend to trend lower as the northern hemisphere harvest approaches, but there is still plenty which can go wrong between now and then.

Have any questions or comments?

We love to hear from you!

Print This Post

Key Points

• Wheat and canola prices have rallied from long term lows.

• Weather issues in Europe and lower corn plantings have provided support.

• If the season progresses normally prices will trend lower in the coming months.
Click on figure to expand

Data sources: Mecardo, Refinitiv

Have any questions or comments?

We love to hear from you!
Close shot of Grain in a field
Grains & Oilseeds

Wheat waits for a trigger

The wheat complex has experienced a rather choppy few days, with systematic profit-taking shifting some of the heat out of the supply-squeeze-driven buoyancy we are

Read More »
Barley
Grains & Oilseeds

Should we be selling wheat?

It’s a bit of an understatement to say there is a bit going on in grain markets at the moment. Here we’ll cover price and

Read More »
Wheat head closeup in a field
Grains & Oilseeds

Black Sea bites back

Finally, we are starting to see the market react in a manner that many of us expected. For weeks, the wheat market largely shrugged off

Read More »
Canola field NSW
Grains & Oilseeds

Demand driving strong canola

Canola prices have bounced back to their recent highs and sit at levels not seen since 2022. Global supply remains solid, with perhaps some tightness

Read More »

Want market insights delivered straight to your inbox?

Sign up to the mailing list to get regular updates to new analysis and market outlooks

Independent analysis and outlook for wool, livestock and grain markets delivered to you as it’s published

Commodity conversations podcast cover image, a illustration of a sheep standing on a cow's back with grain either side
Listen to the podcast

Join the Mecardo team for the Commodity Conversations podcast, where we provide short weekly market recaps and longer conversations with guests to discuss the drivers and trends in livestock, grain and fibre markets.

156A7986_LQ-oxuut6zdthc8o09e5yux8merbgc55xv1zecznd47xo (2)
MEET THE TEAM

Our team of market analysts are recognised as leaders in Australian Ag market analysis, providing invaluable insights to help you navigate the ever-changing commodity landscape. 

SERVICES AND CAPABILITIES STATEMENT BROCHURE

We don’t just bring you the most up to date market insights. Find out more about Mecardo’s services including risk management advisory, modelling, benchmarking, research & consultancy.